401(k) Rollovers Can Be Costly — and Irreversible. What to Know Before Moving Your Money.
Millions of people transfer funds from workplace retirement plans to individual retirement accounts (IRAs) annually. However, mistakes during this process can lead to significant costs and are often irreversible.
Federal law permits tax-free rollovers upon certain events, such as changing jobs or retiring. As the Baby Boomer generation enters retirement, these rollovers have become increasingly common. In 2023 alone, investors rolled $682 billion into IRAs, more than tripling the amount from the early 2000s, with nearly 6 million individuals making the move. Data indicates that a substantial portion of newly opened traditional IRAs are funded solely by 401(k) rollovers.
The IRS has issued guidance aimed at simplifying and expediting the rollover process. Nevertheless, financial advisors warn of several pitfalls that investors might encounter.
Ellen Lander, founder of Renaissance Benefit Advisors Group, notes that the decision to roll over funds or keep them in a 401(k) plan has both advantages and disadvantages, and these are often not sufficiently discussed. Potential risks highlighted by advisors include tax penalties and higher investment fees, which could ultimately reduce an individual's retirement savings.
The CFP Board of Standards has also published a guide addressing common misconceptions about rollovers. Two key myths debunked are that workers are obligated to roll over their assets when changing jobs and that such decisions can be reversed later. In reality, most 401(k) plans allow employees to leave their funds with their former employer, though data shows this is rarely done. Furthermore, once money is rolled into an IRA, it is generally irreversible, as stated in the CFP Board's guide. An exception is the Thrift Savings Plan for federal workers, which has specific provisions for accepting rollovers under certain conditions.
Investors can typically roll over an IRA or an old 401(k) into their new employer's workplace plan when switching jobs.
Fees
Both workplace retirement plans and IRAs involve investment fees. These fees are often deducted automatically, making them less visible to investors. Advisors point out that fees in IRAs are frequently higher than in employer-sponsored plans. This is because employers can negotiate lower fees for their employees by leveraging collective buying power to access "institutional" share classes of mutual funds. Individual IRA investors, lacking this power, typically have access only to more expensive "retail" shares of the same funds. This difference in fees, even a fraction of a percentage point, can significantly impact long-term investment growth due to compounding. A study by The Pew Charitable Trusts estimated that the fee differential could lead to billions in lost savings for retirees over time.
"You can't go back to whence you came."
Brenton Harrison
Certified financial planner based in Nashville
The Securities and Exchange Commission provides an example illustrating the long-term financial impact of fees: an initial $100,000 investment earning 4% annually over 20 years would result in approximately $30,000 more for an investor paying a 0.25% annual fee compared to one paying 1%. It's important to note that this is not always the case, as some 401(k) plans might offer funds with higher fees than comparable IRA options.
Flexibility
IRAs generally offer greater flexibility in terms of investment choices and withdrawal options compared to 401(k) plans. Employers typically provide a limited selection of investment funds within a 401(k). While having a curated list can simplify investment decisions for some, a wider array of choices in an IRA might lead to "choice paralysis" for others. Employers have a fiduciary duty to select investments that are in their employees' best interests. Conversely, financial intermediaries recommending IRA rollovers may not be bound by the same fiduciary standard. For individuals seeking professional asset management, rolling over to an IRA is often necessary to allow for discretionary management by an advisor. While 401(k) participants can still receive investment advice, they must execute trades themselves.
Withdrawal options in retirement can also differ. Many 401(k) plans offer limited installment payment options, whereas IRAs may provide more flexibility. Additionally, 401(k) plans often allow participants to take loans from their accounts, a feature not available with IRAs.
Fresh materials — MMA News
Nvidia's Friday Stock Plunge: Unpacking the Fed's Influence
Nvidia's stock experienced a significant downturn on Friday, shedding billions in market value. The shares, which reached a high of $229.26 during the day, closed at $217.55, a 4.6% drop. This reversal, occurring after a strong earnings report, mirrored a pattern seen wit
Trump-Promoted Freedom Fuel Stations Accused of Selling Unpaid Gas
A lawsuit filed by a Georgia-based fuel supplier, Mansfield Oil, claims that some of the gasoline sold through the Freedom Fuel Network, which received praise from President Donald Trump for its discounted prices, was never paid for. The federal lawsuit, lodged on August 19th, states that b
New Tariff Walls in U.S.-Canada Trade: Economic Implications for Critical Metals
The escalating trade dispute between the U.S. and Canada, marked by significant reciprocal tariffs, is prompting businesses, economists, and investors to reassess economic volatility. The U.S. has imposed a 50% tariff on various Canadian goods, leading to Canada's retaliatory tariffs of $2
Dolly Parton: The Unseen Strength in Being Underestimated
In a 2015 interview, the famously optimistic Dolly Parton candidly discussed a period of personal struggle and depression. She revealed feeling guilty about her success during a time of personal health and professional challenges in the 1980s, following a diagnosis of endometriosis an
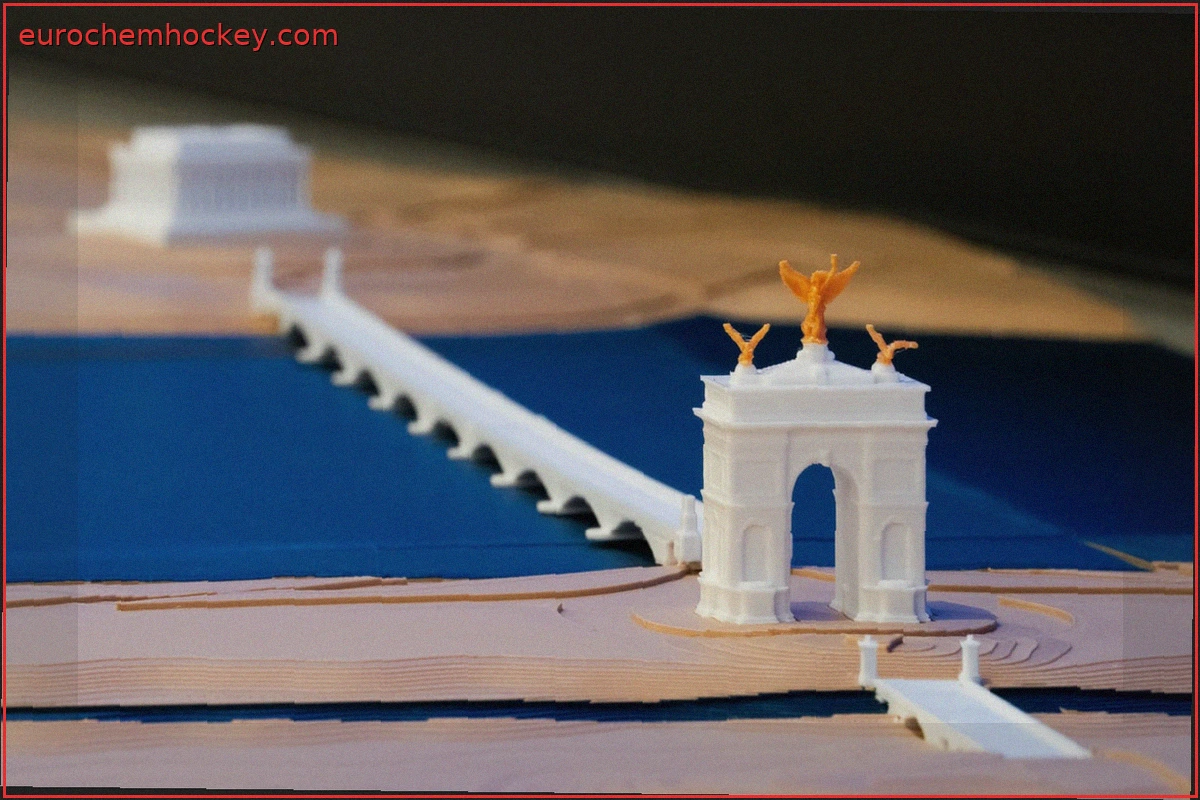
National Park Service Backs Trump's 250-Foot Arch Despite Adverse Effects on Historic Sites
The National Park Service has given its backing to the proposed 250-foot Triumphal Arch by President Donald Trump, including its location and scale. This decision comes despite the agency's own findings that the monument would negatively impact historic properties and sightlines in the
Trump Administration Considers Yosemite Land Swap for Private Developer's Access Road
The Trump administration is reportedly evaluating a land exchange that could involve a portion of Yosemite National Park. The proposed deal would grant a private developer an access road to the park. The Interior Department and legal representatives for the company, Kingsbarn R